
1Why Every Condo Owner Needs Personal Insurance
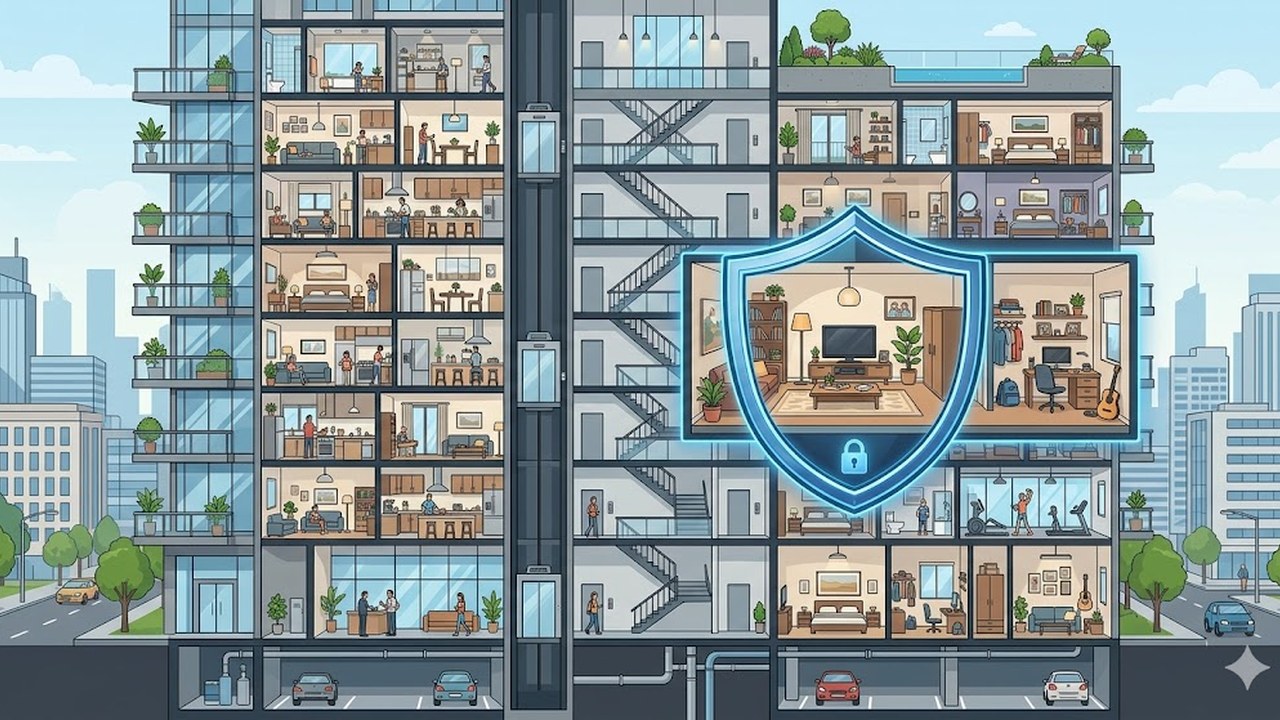
One of the most common misconceptions among condo owners is that the condo corporation's master policy covers everything. It doesn't. The master policy protects the building, its structure, and common areas — but it does not protect you, your belongings, or your financial liability as a unit owner.
Think of it this way: the corporation insures the building. You need to insure yourself.
Without personal condo insurance, a fire, flood, or break-in could leave you replacing every possession out of pocket. A liability claim could wipe out your savings. And a deductible chargeback from the corporation could cost you $50,000 to $250,000 — with no coverage to fall back on.
This guide covers exactly what personal condo insurance protects, how each coverage works, and what you need to get right.
2Personal Property Coverage
Personal property coverage (also called contents coverage) protects your belongings — everything you'd take with you if you moved. This includes:
- Furniture: Sofas, beds, dining tables, desks, bookshelves
- Electronics: TVs, computers, tablets, phones, gaming systems, cameras
- Clothing: Your entire wardrobe, shoes, accessories
- Kitchen: Appliances (if you own them), cookware, dishes, small appliances
- Personal items: Books, sports equipment, musical instruments, artwork, linens
- Items in storage: Belongings in your building's storage locker or parking area
- Items temporarily away from home: Belongings stolen from your car, hotel room, or while travelling (subject to limits)
Choosing Your Coverage Amount
Most people dramatically underestimate what their belongings are worth. A typical one-bedroom condo owner might assume $20,000 — but when you add up every item, the real total is often $40,000 to $80,000+. A two-bedroom with a well-furnished living space can easily reach $60,000 to $120,000.
The best way to set your coverage: do a room-by-room inventory. Walk through your unit, category by category, and estimate replacement costs (what it would cost to buy new, not what you paid originally). Keep the inventory stored in the cloud.
Sub-Limits on Specific Categories
Your policy has maximum limits for certain categories of belongings, regardless of your total coverage amount:
| Category | Typical Sub-Limit |
|---|---|
| Jewelry, watches, gems | $2,000 – $6,000 |
| Cash and securities | $500 – $2,000 |
| Collectibles (stamps, coins, trading cards) | $1,000 – $5,000 |
| Bicycles | $1,000 – $3,000 |
| Wine and spirits | $1,000 – $2,000 |
| Business equipment in home | $2,000 – $5,000 |
If you own items that exceed these sub-limits, you need a scheduled personal articles rider (also called a floater). This rider provides coverage for specific high-value items at their appraised value, often with no deductible and broader protection (including accidental loss).
3Unit Betterments and Improvements
Betterments and improvements coverage protects upgrades and renovations you've made to your unit beyond the standard unit definition — the unit's original condition as it was when the building was first constructed.
The corporation's master policy covers the standard unit. Anything you've added or changed is your responsibility. Examples include:
- Renovated kitchen with custom cabinets, stone countertops, and upgraded appliances
- Bathroom upgrades: new tile, vanity, fixtures, heated floors
- Hardwood or engineered flooring installed over original builder-grade materials
- Custom closet organizers and built-in shelving
- Upgraded lighting fixtures, crown moulding, accent walls
- Smart home systems (thermostat, locks, lighting)
To set your betterments coverage, estimate the total cost to restore all upgrades at current prices. A renovated kitchen alone can be $20,000 to $60,000 to replace. A full condo renovation might total $50,000 to $150,000+. Your betterments coverage should reflect these numbers.
If you haven't done any renovations, you still need some betterments coverage — the standard unit definition in many older buildings may not include modern finishes, and the gap between what the master policy covers and what your unit actually contains may be significant.
4Personal Liability Coverage
Personal liability coverage protects you if someone is injured in your unit or if you accidentally damage someone else's property. It covers:
- Medical expenses for the injured person
- Legal defence costs — even if the lawsuit is frivolous
- Court-awarded damages if you're found liable
- Property damage you cause to others
Why $2 Million Is the Recommended Minimum
Standard policies typically start at $1 million of liability coverage, but $2 million is strongly recommended. Consider these scenarios:
- A guest slips on your wet bathroom floor, hits their head, and suffers a traumatic brain injury. Medical costs, lost income, and pain-and-suffering awards can easily exceed $1 million.
- A fire starts in your unit (a forgotten candle, a faulty appliance) and spreads to adjacent units and common areas, causing extensive damage and displacing multiple residents.
- Your dog bites a visitor, resulting in serious injury and a lawsuit.
The cost difference between $1 million and $2 million of liability coverage is typically only $20 to $40 per year. It's one of the best-value upgrades in all of insurance.
What's Not Covered
- Intentional acts (you deliberately caused harm)
- Business-related liability (you run a business from your condo)
- Motor vehicle incidents (covered by auto insurance)
- Professional services (covered by professional liability insurance)
5Loss Assessment Coverage
Loss assessment coverage is unique to condo insurance and protects you from two types of financial charges:
Deductible Chargebacks
When a covered loss originates in your unit — a water leak, a fire, an appliance failure — the condo corporation may charge you the master policy's deductible. This is the most common and most expensive type of loss assessment. Deductibles in Canadian condos range from $10,000 to $250,000+, with water damage deductibles being the highest.
Special Assessments for Insured Losses
If the corporation levies a special assessment to cover costs related to an insured loss (for example, the deductible from a fire that damaged common areas), your loss assessment coverage pays your share of that assessment.
How Much Do You Need?
Your loss assessment coverage should match the highest deductible on the corporation's master policy. Contact your property manager and ask for the current deductible amounts — especially for water damage, fire, and general liability. Set your coverage accordingly.
Many policies include a default of $10,000 to $25,000 in loss assessment coverage. If your corporation's water damage deductible is $100,000, that default leaves you $75,000 to $90,000 short. Increasing your coverage typically costs only $50 to $150 more per year.
6Additional Living Expenses (ALE)
If a covered loss makes your unit uninhabitable — fire, major water damage, structural issues — your additional living expenses coverage pays for reasonable costs of living elsewhere during repairs:
- Hotel or temporary rental: Reasonable accommodation costs for you and your family
- Meals: The increased cost of eating out versus cooking at home
- Laundry: If you no longer have access to in-unit or in-building laundry
- Pet boarding: If your temporary accommodation doesn't allow pets
- Storage: If undamaged belongings need to be stored during restoration
- Other reasonable expenses: Additional transportation costs, moving expenses
Coverage Limits
ALE is typically capped at 20% to 30% of your contents coverage and has a time limit — usually 12 to 24 months. On a policy with $60,000 of contents coverage, your ALE limit might be $12,000 to $18,000.
For condo owners in expensive rental markets like Toronto and Vancouver, this cap can be insufficient. If your unit will take 6 months to restore and temporary housing costs $2,500/month, you'll need at least $15,000 in ALE coverage. Review your limit and increase it if needed.
Important Rules
- Keep all receipts. Every expense must be documented.
- "Reasonable" is the standard. Your insurer will cover comparable accommodation — not a luxury upgrade.
- The coverage pays the difference. ALE covers the increased cost of living — so if your normal food costs are $500/month and restaurant meals cost $800/month during displacement, ALE covers the $300 difference.
7Optional Endorsements Worth Adding
Beyond the core coverages, consider these endorsements that address common gaps:
Sewer Backup
Standard condo policies exclude sewer backup damage. If sewage enters your unit through floor drains or plumbing fixtures, you need this endorsement. Cost: $30 to $100 per year. This is especially important for ground-floor and below-grade units.
Overland Water
Protects against flooding from external sources entering through your unit's windows or doors. Most relevant for ground-floor units. Cost: $50 to $200 per year.
Earthquake
Covers earthquake damage to your unit contents and improvements. Essential in BC and the Quebec/Ottawa corridor. Cost varies by region: $50 to $400+ per year.
Identity Theft
Covers expenses related to identity theft recovery — legal fees, lost wages, credit monitoring. Cost: $25 to $75 per year.
Scheduled Personal Articles
Provides full-value coverage for high-value items (engagement rings, watches, art, musical instruments) that exceed your policy's sub-limits. Covers more risks than your base policy, including accidental loss. Cost depends on item value.
8What Condo Insurance Does NOT Cover
No insurance covers everything. Here's what your condo policy excludes:
- Building structure and common areas: Covered by the corporation's master policy, not yours
- Wear and tear: Gradual deterioration of your unit finishes, appliances, or belongings is maintenance, not an insurable event
- Pest infestations: Bed bugs, mice, cockroaches — these are maintenance and habitability issues, not covered losses
- Gradual water damage: A slow leak that causes damage over weeks or months is classified as neglect, not a sudden event
- Intentional damage: Any damage you cause deliberately
- Business operations: If you run a business from your condo, standard personal insurance excludes business-related claims. You need a home business endorsement or separate commercial policy.
- Short-term rental activity: If you rent your unit on Airbnb or similar platforms, your standard condo insurance may not cover claims that occur during a rental period. You may need specialized short-term rental coverage.
- Flood and earthquake: Unless you add the specific endorsements
- Nuclear, war, terrorism: Standard exclusions on all policies
9Final Thoughts
Condo insurance is affordable, essential, and widely misunderstood. Your corporation's master policy covers the building — but without personal insurance, your belongings, your unit improvements, your liability, and your exposure to the corporation's deductible are all unprotected.
The most important steps: do a proper contents inventory to set your coverage accurately, check your corporation's master policy deductibles and match your loss assessment coverage accordingly, add sewer backup coverage, and set your liability to at least $2 million. At an average cost of $300 to $800 per year, condo insurance is one of the most valuable financial protections a Canadian property owner can have.
Frequently Asked Questions
Condo insurance covers five main areas: your personal belongings (furniture, electronics, clothing), improvements and upgrades you've made to your unit beyond the original standard finishes, personal liability if someone is injured in your unit, loss assessments charged by the condo corporation (including deductible chargebacks), and additional living expenses if your unit becomes uninhabitable due to a covered loss.
Yes, with important caveats. Your condo insurance covers water damage to your belongings and unit improvements from sudden events like burst pipes or appliance failures. However, sewer backup damage requires a separate endorsement, and gradual water damage from maintenance neglect is excluded. If a leak from your unit damages another unit, your loss assessment coverage handles the corporation's deductible charged to you.
Yes. Your personal property coverage protects your belongings against theft, whether from a break-in to your unit or theft from your car, storage locker, or while travelling (up to policy limits for off-premises theft). High-value items like jewelry, watches, and collectibles are subject to sub-limits — typically $2,000 to $6,000 per category — unless you add a scheduled articles rider for higher coverage.
Yes. Items in your building's storage locker are generally covered under your personal property coverage, as the locker is considered an extension of your unit. However, there may be sub-limits for certain items, and if the storage area has a higher risk of water damage or theft, your insurer may apply restrictions. Check your policy for any specific limitations on contents stored outside your unit.
Without condo insurance, you are personally responsible for replacing all your belongings after a loss (fire, theft, water damage), paying for any damage to unit improvements or renovations, covering the condo corporation's deductible if a claim originates in your unit (potentially $50,000 to $250,000+), defending yourself against liability claims with your own money, and finding and paying for temporary housing if displaced. A single incident could result in tens of thousands of dollars in uninsured costs.
Get your condo insurance quote in 90 seconds — coverage starts from $20/month.
Get Your Quote